A Practical Guide to Selling a Bangor, Maine Home: Timing, Costs, and Sale Paths
Selling a home in Bangor, Maine involves more than choosing a list price. From snowy winters and older housing stock to moving plans and repair needs, the right approach depends on the property and the seller’s priorities. Homeowners who need a quick house sale in Bangor, ME, may evaluate options differently from sellers who have time to prepare, market, and negotiate. A clear plan starts with realistic expectations. The strongest choice is not always the option with the highest advertised price. It is the path that best balances likely proceeds, required repairs, time to close, risk of delays, and the practical demands of the next move.
What Bangor’s Market Means for Sellers
Local market reports can be useful, but they should be treated as context rather than a promise of what any one home will sell for. Different services may show different results because they measure different date ranges, property types, and transaction data. When buyers have more homes to consider, accurate pricing, clean presentation, and flexibility around showings can become especially important.
Choosing the Right Time to Sell
There is no universally perfect month to sell in Bangor. Spring and summer can make landscaping, daylight, and curb appeal easier to showcase. Fall can appeal to buyers trying to settle before winter. Winter sales may involve fewer casual shoppers, but serious buyers may still be active. A home’s condition, carrying costs, job changes, school schedules, and purchase plans often matter more than waiting for a seasonal peak. Owners whose move extends beyond Maine may also need a wider transition plan. For example, someone relocating south or west may compare a Bangor sale with options to Sell Your House In New Hampshire when coordinating more than one property, closing date, or household move.
See also: Designing Outdoor Spaces That Match Your Lifestyle
Four Common Ways to Sell a Bangor Home
1. Listing With a Real Estate Agent
A traditional listing commonly involves setting a price, photographing the property, scheduling showings, reviewing offers, negotiating inspection matters, completing an appraisal if the buyer is financing, and closing. This route may fit sellers who can prepare the home and allow time for marketing. Before signing, review the listing term, compensation structure, cancellation terms, and the agent’s marketing plan.
2. Selling the Home Yourself
A for-sale-by-owner transaction gives the owner more control over advertising, showings, buyer communication, and negotiation. It also requires the seller to handle pricing research, screening inquiries, scheduling access, and document coordination. Professional legal guidance can be valuable, particularly when contracts, title questions, estates, or unusual property features are involved.
3. Selling to a Cash Buyer
A direct cash sale can reduce the need for repeated showings and may avoid delays tied to a buyer’s mortgage approval. It can be useful for a vacant house, an inherited property, or a home needing substantial work. In exchange for convenience and speed, the offer may be lower than the amount a fully repaired home could potentially command after broad market exposure. Request every offer in writing, including price, fees, closing date, inspection rights, and contingencies.
4. Renting or Holding the Property
Keeping the property can be another option, but it creates landlord responsibilities. Consider management costs, maintenance, vacancy periods, insurance, tenant screening, taxes, and the time needed to respond to repairs. Holding a home is not automatically more profitable than selling, particularly if the property needs work or the owner no longer lives nearby.
Costs That Can Change Final Proceeds
The offer price is only the starting point. Sellers should estimate their likely net proceeds by accounting for the mortgage payoff, real estate compensation or listing fees, attorney and title charges, property taxes, repair credits, cleaning, hauling, storage, moving, and any liens or recorded claims. Tax consequences can vary by household and ownership history so that a qualified tax professional can help with questions specific to the seller’s circumstances.
Preparing a Home for Sale
Preparation does not have to mean a full renovation. Focus first on issues that affect safety, maintenance, and buyer confidence. A practical Bangor preparation plan includes:
- Removing clutter from entryways, living areas, kitchens, and storage spaces.
- Repairing obvious hazards, such as loose railings, damaged steps, or faulty fixtures.
- Addressing active leaks, visible water damage, and plumbing concerns.
- Cleaning floors, windows, kitchens, bathrooms, and basement areas.
- Improving lighting in dark rooms and exterior entry points.
- Collecting permits, warranties, utility records, repair invoices, and service records.
- Getting more than one estimate before committing to major repairs.
How Property Condition Affects the Plan
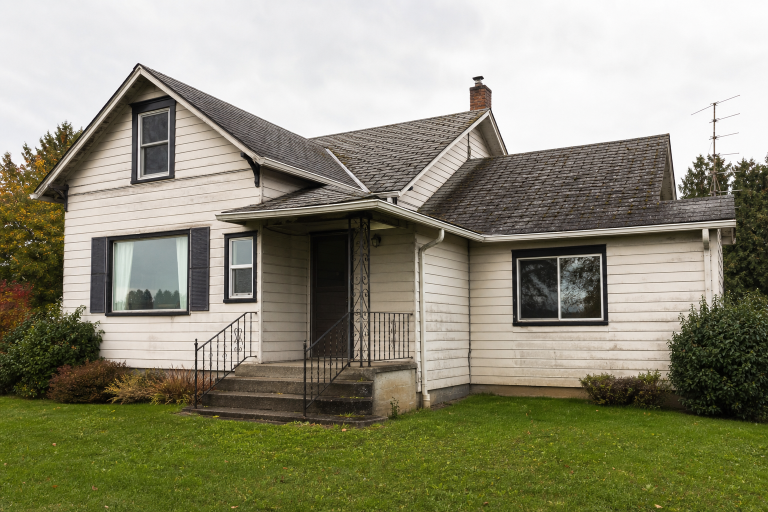
Move-in-ready homes may have a broader pool of interested buyers, while homes with deferred maintenance may call for a different strategy. Bangor sellers should distinguish between cosmetic projects and problems that could affect financing, safety, or future ownership.
- Move-in ready: A traditional listing or private sale may allow the seller to seek broad buyer interest.
- Minor updates needed: Selective painting, cleaning, and small repairs may improve presentation without requiring a major remodel.
- Major repairs needed: An as-is listing, investor sale, or renovation plan may be worth comparing, especially when roof, heating, moisture, insulation, or structural issues are involved.
- Estate, rental, or vacant property: Confirm access, insurance, authority to sell, and the condition of systems before deciding how to market the home.
How to Compare Offers
Compare complete terms rather than focusing only on the highest number. A lower offer with a dependable closing date and fewer conditions can sometimes be more workable than a higher offer that depends on financing, an appraisal, extensive repairs, or a lengthy timeline. Review the price, financing type, earnest money, inspection and appraisal contingencies, seller-paid costs, requested credits, possession date, and cancellation rights.
Bangor Closing Details to Check
Bangor’s citywide revaluation became effective for the April 1, 2026, assessment date, so sellers should review current assessment and tax information as part of their closing preparation. The city explains the assessment process and timeline in its revaluation guidance for Bangor property owners. An assessed value is used for tax purposes and may not match the price a willing buyer would pay in a particular sale. Also confirm the legal owner, mortgage payoff information, unpaid taxes, liens, easements, shared driveways, boundaries, permits, and probate matters. Maine law generally requires sellers of residential property to provide purchasers with a disclosure statement covering items such as water supply and heating information, subject to statutory exemptions. Reviewing Maine’s residential property disclosure requirements early can help prevent last-minute document issues.
A Simple Selling Checklist
- Set a target closing date and estimate the funds needed after closing.
- Gather loan, tax, insurance, utility, and repair records.
- Identify urgent repairs separately from optional improvements.
- Compare at least two potential sales paths.
- Request written estimates for significant work.
- Review every offer condition and estimated net amount.
- Confirm title, disclosure, and closing requirements before signing.
- Keep copies of every signed agreement and closing document.
Final Thoughts
The best way to sell a Bangor home depends on more than speed or list price. Homeowners should consider the property’s current condition, local market activity, desired timeline, repair needs, selling method, closing expenses, and any legal or ownership details that could affect the transaction. Comparing these factors can help sellers understand the potential advantages and trade-offs of a traditional listing, as-is sale, for-sale-by-owner approach, or cash offer. It is also important to look beyond the headline offer and estimate the likely net proceeds after paying off the mortgage, covering closing costs, repairs, taxes, liens, and other expenses. By reviewing the complete financial and practical picture, homeowners can choose a selling strategy that fits the property, their financial priorities, and the next stage of life while approaching the transaction with clearer expectations.